Perpetual Funding Rate Mark Price Math
Incremental Partial Liquidation Engines: Tier Step-Down & Order Slicing Specs
Rather than dumping an entire $40 million whale position onto the orderbook in a single market cascade, modern incremental liquidation engines cancel open orders and shave slices step-by-step down notional MMR brackets.
In legacy first-generation crypto derivatives venues (2016–2020), crossing your Liquidation Trigger Price (P_liq) by one single tick ($0.50) triggered an atomic 100% full-position confiscation: a $30,000,000 whale account was seized in its entirety and dumped onto the live orderbook, triggering cascading flash crashes! Today's institutional perpetual engines implement Multi-Stage Incremental (Partial) Liquidation Waterfalls designed to restore account solvency with the minimum possible market impact: first cancelling margin-locking open orders, then shaving just enough notional to drop the account one Maintenance Margin Bracket lower, before ever resorting to full bankruptcy takeover!
Within our Perpetual Futures Funding Clamps, Mark Price and ADL Master Guide under the Perpetual Swap Funding Clamps, Impact Margin Notional, Mark Price & ADL hub, read this engine teardown alongside Tiered Maintenance Margin Notional Brackets and Exchange Insurance Fund Inflow & Depletion.
The Four-Stage Incremental Liquidation Waterfall (UniMMR >= 100%)#
Trace the exact deterministic state machine executed inside a modern perpetual matching engine the millisecond an account's Maintenance Margin Ratio (MM / Margin_Balance) reaches 100.0%:
- Stage 1 — Instant Open-Order Cancellation (
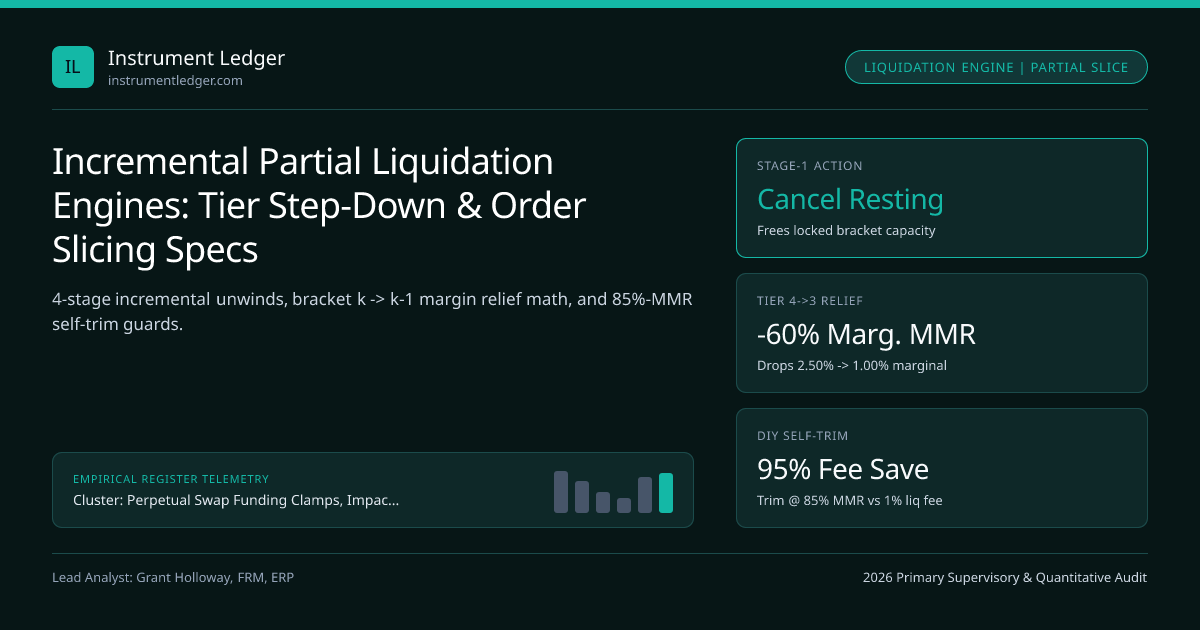
t + 0ms): Cancel all resting margin-increasing limit orders across the account. If releasing order-locked margin dropsAccount_MMR < 100%(or lowers the notional bracket tier!), liquidation halts right here with ZERO position closed! - Stage 2 — Bracket Tier Step-Down Slice: For any position in Bracket Tier
k >= 2, calculate the exact notional excessDelta_N = Current_Notional - Upper_Bound(Tier_{k-1}). Submit a reduce-only IOC/TWAP order closing onlyDelta_N! Dropping from Tier 4 (2.50% MMR) down into Tier 3 (1.00% MMR) slashes required marginal maintenance margin by 60%—frequently restoring the remaining position to full health! - Stage 3 — Proportional Multi-Symbol Cross Shaving: In Unified Portfolio Margin, slice
5%–20%increments starting with the highest-liquidity pairs (BTCUSDT,ETHUSDT) or highest delta contributors untilUniMMRfalls safely back to85%–90%. - Stage 4 — Terminal Tier-1 Takeover / Backstop Vault Handoff: Only if price continues crashing until the residual position sits inside Bracket Tier 1 (or gaps straight past
P_bank) does the engine execute a final full takeover into the Insurance Fund / Backstop Liquidator Vault!
Exact Bracket Step-Down Margin Relief Math#
Let's verify mathematically why closing just $2,000,000 out of a $7,000,000 position under Perpetual Contract Funding Rate Convention tiered brackets instantly rescues the remaining $5,000,000 position—and saves the trader thousands in unnecessary clearance fees!
Worked Whale Bracket Step-Down & Margin Rescue Calculation#
- PostSliceRequiredMM = TierCeiling(k - 1) * MMR{k-1} - cum{k-1}
- NetEquityAfterPartialSlice = PreSliceEquity - ( DeltaN * ( SlippagePct + PartialClearanceFee_Pct ) )
- Worked $7,000,000 BTCUSDT Whale Rescue (Tier 4: >$5M @ 2.50% MMR, cum4 = $80,250; Tier 3 Ceiling = $5M @ 1.00% MMR, cum3 = $5,250):
- Pre-Slice Required MM = ($7,000,000 * 2.50%) - $80,250 = $94,750.00; Trigger fires as Equity dips to $94,500.00!
- Engine shaves ONLY Delta_N = $7,000,000 - $5,000,000 = $2,000,000 (charging 0.75% partial liq fee + 0.05% slip = -$16,000):
- Post-Slice Equity = $94,500 - $16,000 = $78,500.00!
- Post-Slice Required MM on Remaining $5,000,000 (now Tier 3!) = ($5,000,000 * 1.00%) - $5,250 = $44,750.00!
- Result: $78,500 Equity >> $44,750 Required MM (MMR drops from 100.3% to 57.0%!) -> $5,000,000 Position SAVED!
Full-Takeover vs Incremental vs On-Chain Backstop Liquidation Specs#
Compare liquidation engine execution designs across CEXs, on-chain CLOBs (Hyperliquid HYPE, dYdX), and regulated futures intraday calls:
| Engine Architecture | Trigger Threshold | Position Unwind Granularity | Clearance Fee Assessment | Market Cascade Footprint |
|---|---|---|---|---|
| Legacy Full Takeover | Equity <= MM (100%) | 100% Atomic Seizure | Confiscates 100% equity above P_bank | Severe (Whale market dumps) |
| CEX Incremental Bracket | Equity <= MM (100%) | Tier-by-Tier Delta_N Slices | 0.5%–1.5% strictly on Delta_N! | Low (TWAP / IOC bounded slices) |
| Unified PM Percentage | UniMMR >= 100% | 5%–10% slices to restore 90% MMR | Partial fee on sliced legs only | Smooth multi-asset de-risking |
| Hyperliquid CLOB -> HLP | Equity <= MM (Book) / 2/3 MM (Backstop) | Book order first; HLP backstop at <2/3 MM | Zero fee on book liq! Surplus in HLP | Transparent 2-tier CLOB + Vault |
Why Every Institutional OMS Runs a Local 85% MMR Self-Trim Daemon#
Look closely at the fourth bar above! Even the gentlest incremental exchange liquidation engine still charges a 0.50% to 1.50% punitive Liquidation Clearance Fee on the sliced $2,000,000 ($10,000–$30,000 penalty!) AND freezes your API keys (ERROR: Account in liquidation state) while the engine controls your account! By running your own local Pre-Liquidation Guard that monitors live UniMMR (calibrated via our Intraday 0DTE Sigma Band Calculator) and proactively trims 15% of size whenever UniMMR crosses 85.0%, you achieve the exact same bracket tier step-down paying normal 0.02%–0.05% VIP trading fees—saving 95% of the liquidation penalty!
Frequently asked questions
Why did the exchange cancel all my resting take-profit and grid limit orders right before partially liquidating me?
Stage 1 of every incremental liquidation engine cancels open orders to free locked Initial Margin and reduce Open-Order Bracket Notional. Frequently, cancelling resting orders alone drops your bracket tier enough to abort position liquidation altogether.
Why could my trading bot not submit a hedge or cancel orders during a partial liquidation?
The millisecond Account MMR hits 100%, the risk engine places an exclusive mutex lock ("Liquidating State") on the sub-account so user orders cannot race or conflict with the engine reduce-only slicing orders until MMR drops back below threshold.
Does partial liquidation work if my entire position is already inside the smallest Bracket Tier 1?
On standard CEX isolated contracts, if your position is already inside Tier 1 (e.g., <$250,000 on BTCUSDT), there is no lower MMR bracket to step down into, so breaching Tier-1 Maintenance Margin triggers a full position liquidation.
How does Hyperliquid two-stage liquidation differ from centralized exchange partial liquidation?
When equity falls below 100% Maintenance Margin (but stays above 2/3 MM), Hyperliquid sends market/IOC reduce orders directly to the CLOB with zero liquidation penalty, keeping remaining equity in the user account; only below 2/3 MM does the HLP vault take over.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Grant Holloway, FRM, ERP
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Grant Holloway, FRM, ERP. (2026, November 14). Incremental Partial Liquidation Engines: Tier Step-Down & Order Slicing Specs. Instrument Ledger. https://instrumentledger.com/specs/incremental-partial-liquidation-engine-twap-order-slicing-rulesRelated Perpetual Funding Rate Mark Price Math & Institutional Briefings
Explore Perpetual Funding Rate Mark Price Math Hub (20) →Perpetual Funding Rate Mark Price Math
Perpetual Futures Funding Clamps, Impact Margin Notional, Mark Price and ADL GuidePerpetual Funding Rate Mark Price Math
Pre-Market Perpetual Futures Specs: Internal EWMA Oracles & Spot TransitionPerpetual Funding Rate Mark Price Math
Perpetual Funding vs Quarterly Dated Futures Implied Repo: Term-Structure MathPerpetual Funding Rate Mark Price Math
Regulated Perpetual-Style Futures Specs: CFTC, Cboe, SGX & CCP ClearingPerpetual Funding Rate Mark Price Math
8-Hour Perpetual Funding Formula: F = P + clamp(I - P, -0.05%, +0.05%) MathPerpetual Funding Rate Mark Price Math
1-Hour Discrete vs Continuous Block-Level Perpetual Funding Accrual SpecsPerpetual Funding Rate Mark Price Math
Impact Bid and Impact Ask Prices: L2 Depth-Weighted Impact Margin Notional MathPerpetual Funding Rate Mark Price Math
Three-Component Perpetual Mark Price Median: Preventing Wick LiquidationsSpan2 Portfolio Margin Cross Offsets
Spot-Month Delivery Margin Step-Up Specs: FND to LTD Full-Value SurchargesSpan2 Portfolio Margin Cross Offsets
FCM Day-Trade Margin vs Exchange SPAN 2: 15:45 CT Auto-Liquidation TrapsSpan2 Portfolio Margin Cross Offsets
LCH SwapClear OTC IRS vs CME Eris SOFR Swap Futures: 2-Day vs 5-Day MPOR MathLimit Up Limit Down Circuit Breakers
US Equity Market-Wide Circuit Breakers (MWCB): 7%, 13%, 20% & 15:25 ET Rules
Instrument Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.