Span2 Portfolio Margin Cross Offsets
CME SPAN 2 Portfolio Margin, VaR Pods, Spread Offsets and Intraday Calls Guide
Global futures clearinghouses have retired static 16-scenario SPAN risk arrays in favor of full-revaluation Historical Value-at-Risk (SPAN 2, Eurex Prisma, ICE IRM 2) engines integrating anti-procyclicality floors, concentration add-ons, and cross-margin offsets.
Across thirty-five years of derivatives clearing (1988–2023), the Standard Portfolio Analysis of Risk (SPAN) model governed trillions of dollars of initial margin using pre-computed 16-scenario contract risk arrays supplemented by manual pairwise spread credit tables. Yet April 2020's negative -$37.63 NYMEX WTI crude oil settlement and March 2022's European natural gas volatility exposed structural blind spots in static grid arrays—driving CME Clearing, Eurex Clearing, and ICE Clear to transition global futures and options clearing onto full-portfolio Historical Value-at-Risk (HVaR) architectures led by the CME SPAN 2 Margin Architecture.
Within the CME SPAN 2 VaR Margin, Inter-Commodity Spread Credits & Intraday Calls pillar, institutional treasury and execution quants audit how clearinghouses decompose Initial Margin (IM) into Pod-Level Filtered HVaR, Stress VaR (SVaR), Liquidity and Concentration Add-Ons (LCA), and Cross-CCP Offsets, while reconciling twice-daily cash variation sweeps and carry inputs inside our Listed Contract Basis and Implied Repo Calculator and Intraday 0DTE Sigma Band Calculator.
From Legacy 16-Scenario Arrays to SPAN 2 Pod-Based HVaR#
Under the legacy CME SPAN Margin Model, each contract's Price Scan Range and Volatility Scan Range were evaluated independently across 16 discrete shocks before applying a complex hierarchy of Intra-Commodity Tier Spread Charges and Inter-Commodity Credit Percentages. Under CME SPAN 2, contracts are grouped into correlated Product Pods (Energy, Interest Rates, Equities, Metals, Agriculture, FX, Crypto) where thousands of historical and stress-period joint return vectors reprice the entire pod portfolio simultaneously—automatically capturing curve twists, crack-spread basis correlations, and option smile convexity without manual pairwise lookup tables! Trace the exact mathematical cutover in Legacy 16-Scenario SPAN vs SPAN 2 HVaR Migration, SPAN 2 EWMA Volatility Floor and APC Scaling Math, and SPAN 2 Stress VaR Tail Calibration.
Additive Margin Decomposition & Worked Energy Pod Audit#
Every clearing statement generated by CME Clearing under CFTC Regulation 39.13 and CPMI-IOSCO PFMI separates Core Market Risk from idiosyncratic whale liquidation costs described in SPAN 2 Liquidity and Concentration Add-On (LCA) and Short Option Minimum (SOM) Tail Floors:
Worked NYMEX Energy Refinery Pod Margin Calculation#
- AggregatedCoreVaR = Sqrt( Summ Sumn [ rho{m,n} * PodMarketRiskm * PodMarketRisk_n ] )
- TotalSPAN2InitialIM = AggregatedCoreVaR + LiquidityConcentrationAddOn (LCA) + SpotDeliveryAddOn + SOMFloor
- Worked NYMEX Energy Refinery Hedge Margin Verification (Long 3,000 CL WTI / Short 2,000 RB Gasoline / Short 1,000 HO ULSD):
- Standalone Unhedged Leg VaR Sum = $19,800,000 (CL) + $13,600,000 (RB) + $7,400,000 (HO) = $40,800,000 Gross IM
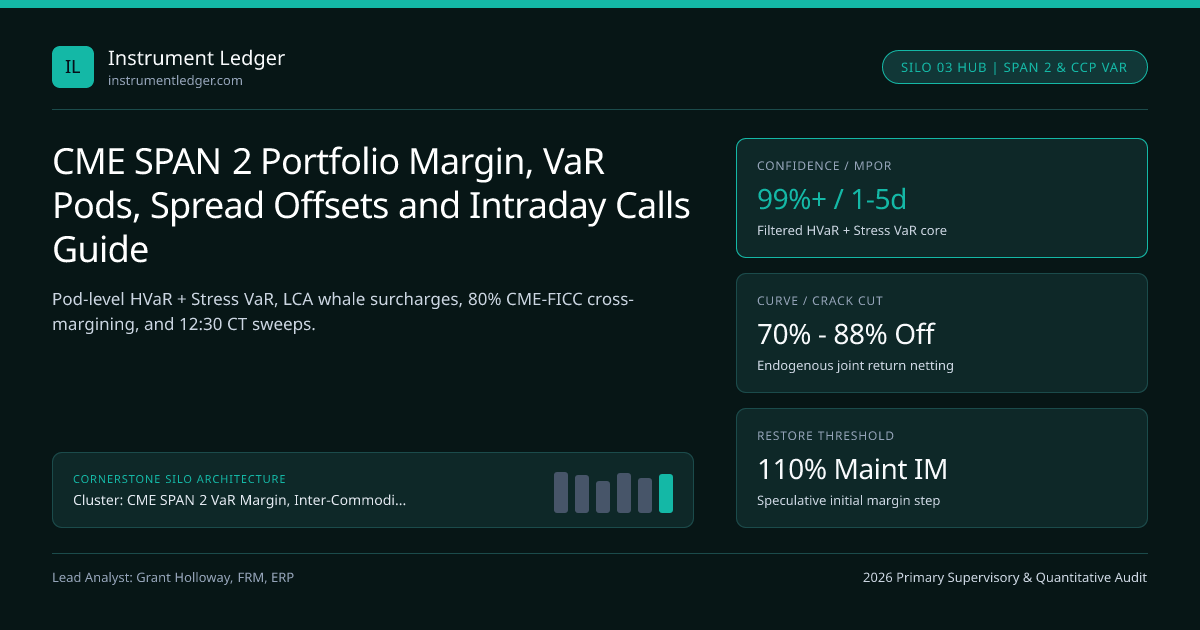
- Endogenous SPAN 2 Energy Pod Joint HVaR + SVaR (Capturing 3:2:1 Crack Correlation) = $8,160,000 (80.0% Spread Offset!)
- Liquidity & Concentration Add-On (LCA for 3,000-lot WTI/Product Footprint) = +$1,140,000
- Required Maintenance Margin = $9,300,000 | FCM Customer Initial Margin (110% Spec) = $10,230,000!
Global Clearinghouse Portfolio Margin Model Comparison#
Compare how major global Derivatives Clearing Organizations (DCOs / CCPs) parameterize confidence intervals, Margin Period of Risk (MPOR), and anti-procyclicality (APC) under ESMA, BaFin, FCA, and CFTC supervision:
| Clearinghouse & Engine | Statistical Core | Confidence & MPOR | Anti-Procyclicality (APC) | Flagship Cross-Product Offset |
|---|---|---|---|---|
CME Clearing (SPAN 2) | Filtered HVaR + Stress VaR | 99%, 1–2d (Fut) / 5d (OTC) | Stress VaR blend + Vol Floor | CME-FICC Treasury Repo (up to 80%) |
Eurex (Prisma) | Filtered Hist. Sim + Monte Carlo | 99.0% (Listed) / 99.5% (OTC), 2–5d | EMIR 25% Buffer / 10yr lookback | Bund/Bobl/Schatz + Eurex IRS (75%+) |
ICE Clear (IRM 2) | Filtered HVaR + Tail Expected Shortfall | 99.0%+, 1–2d Energy | Volatility floor + Stress scenarios | Brent / Gasoil / Dutch TTF pods |
OCC (STANS) | 10,000-Path Copula Monte Carlo | 99% Expected Shortfall, 2d | GARCH/EWMA scale floor | SPX Options vs Index Futures |
LCH (SwapClear) | Filtered Expected Shortfall (ES) | 99.7%, 5–7d Cleared IRS | 10yr unweighted + Stress | Multi-currency OIS/SOFR curve |
Complete Institutional Guide to Spread Offsets, CCP Counterparts & FCM Operations#
Navigate all nineteen quantitative specifications inside this silo to engineer capital-efficient portfolios and survive intraday clearing sweeps:
- Inter-Commodity, Intra-Curve & Cross-CCP Offsets: Audit refinery margins in NYMEX 3:2:1 Crack Spread Offsets, fixed-income butterfly/steepener ratios in CBOT Treasury Yield Curve Spreads (TUT, NOB, FYT), sovereign basis netting in CME-FICC GSD Cash-Futures Cross-Margining, seasonal storage tiers in Intra-Commodity Calendar Spread Charges, and swap-vs-future MPOR savings in LCH SwapClear vs Eris SOFR Margin Efficiency.
- International CCP Frameworks: Compare European EMIR Article 28 anti-procyclicality rules in Eurex Prisma Filtered Historical Simulation, global energy clearing in ICE IRM 2 Brent, Gasoil and TTF Margin, and US equity-option copulas in OCC STANS Monte Carlo vs CME Equity Margin.
- Intraday Variation Sweeps, Collateral & FCM Risk Controls: Master the 1.10x restoration cliff in Initial vs Maintenance Margin 110% Rule, midday bank wires in CME 12:30 CT Intraday Variation Settlement, customer protection in CFTC Rule 39.13 Gross Margin & LSOC, sovereign/gold haircuts in Non-Cash Collateral Schedules (T-Bills, Gold, IEF), expiry add-ons in Spot-Month Delivery Margin Step-Ups, and retail broker traps in FCM Intraday Auto-Liquidation & Day-Trade Margin.
Frequently asked questions
Why did CME Group replace legacy SPAN (1988) with SPAN 2 across Energy, Rates, and Equities?
Legacy SPAN evaluated only 16 fixed price/volatility scenarios per contract and relied on static pairwise spread tables—struggling during April 2020 negative WTI crude prices, complex multi-leg option skew shifts, and concentrated whale positions requiring super-linear Liquidity Add-Ons.
Can institutional traders post US Treasury Bills instead of cash for CME SPAN 2 Initial Margin?
Yes! FCMs and CME Clearing accept US Treasury Bills, Notes, and IEF money-market funds (with small 0.5%–3.0% haircuts) to satisfy Initial Margin, allowing funds to earn full risk-free SOFR yield—though daily Variation Margin losses must still settle in cash.
Why do cleared interest rate futures require ~55% less Initial Margin than economically identical cleared OTC swaps?
Under CFTC Regulation 39.13 and PFMI standards, liquid exchange-traded futures use a 1-to-2-day Margin Period of Risk (MPOR), whereas bilateral/cleared OTC swaps at LCH or CME IRS mandate a 5-day MPOR (scaling VaR roughly by sqrt(5 / 2) = 1.58x).
What is the Liquidity and Concentration Add-On (LCA) in CME SPAN 2?
Core VaR assumes a portfolio can liquidate at mid-market within 1–2 days. Once a fund position exceeds market Average Daily Volume (ADV) thresholds, LCA adds a super-linear bid-ask and market-impact charge reflecting the true multi-day cost of unwinding a whale book.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Grant Holloway, FRM, ERP
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Grant Holloway, FRM, ERP. (2026, November 14). CME SPAN 2 Portfolio Margin, VaR Pods, Spread Offsets and Intraday Calls Guide. Instrument Ledger. https://instrumentledger.com/specs/cme-span-2-var-portfolio-margin-inter-commodity-offsets-guideRelated Span2 Portfolio Margin Cross Offsets & Institutional Briefings
Explore Span2 Portfolio Margin Cross Offsets Hub (20) →Span2 Portfolio Margin Cross Offsets
Legacy 16-Scenario SPAN Risk Arrays vs CME SPAN 2 HVaR ArchitectureSpan2 Portfolio Margin Cross Offsets
SPAN 2 EWMA Volatility Scaling & Anti-Procyclicality (APC) Margin FloorsSpan2 Portfolio Margin Cross Offsets
SPAN 2 Stress VaR Calibration: Historical Crisis Scenarios in Energy & RatesSpan2 Portfolio Margin Cross Offsets
CME SPAN 2 Liquidity and Concentration Add-On (LCA): Whale Margin MathSpan2 Portfolio Margin Cross Offsets
NYMEX 3:2:1 Crack Spread Specs: WTI, RBOB & ULSD Unit Conversion & MarginSpan2 Portfolio Margin Cross Offsets
CBOT Treasury Yield Curve Spreads (TUT, NOB, FYT): DV01 Ratios & SPAN 2Span2 Portfolio Margin Cross Offsets
CME-FICC Cross-Margining Specs: Cash Treasury Repo vs CBOT Futures OffsetsSpan2 Portfolio Margin Cross Offsets
Eurex Clearing Prisma Margin Specs: Filtered HVaR & Bund-Swap OffsetsLimit Up Limit Down Circuit Breakers
Market-Wide Circuit Breakers, LULD Bands, CME Velocity Logic & Halt Specs GuideCfd Index Dividend Roll Contract Specs
Cash vs Forward Index CFDs, Ex-Dividend Adjustments & Commodity Roll Specs GuideFutures Tick Value Delivery Settlement
CME E-mini (ES) vs Micro E-mini (MES) S&P 500 Multipliers and Tick Value SpecsMarket Insights
CME Group: A Great Business With Too Much Success Already Priced In (NASDAQ:CME) - Seeking Alpha
Instrument Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.